What is the scope and industry significance of the Isolation Valves Market?
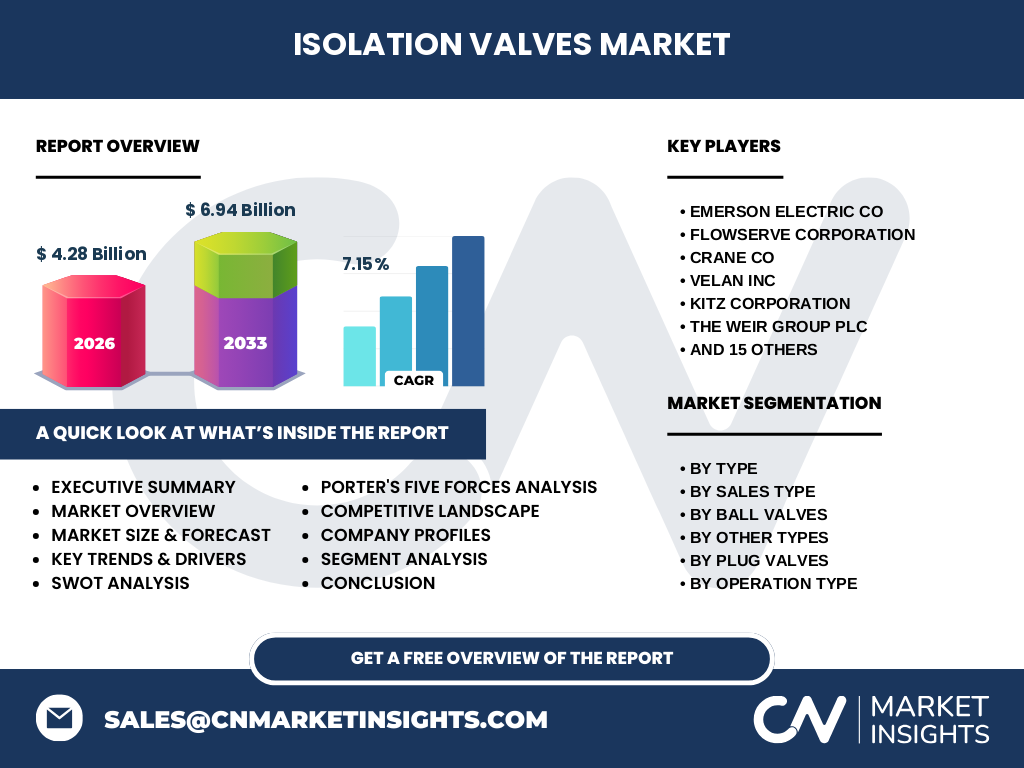
Our analysis indicates that the Isolation Valves Market is valued at $4.28 Billion in 2026, serving as a critical infrastructure backbone. These devices provide absolute shutoff capabilities in fluid processing networks, safeguarding hazardous operations across severe service environments regulated by OSHA and ISO.
Structural Growth Drivers and Market Constraints
The market is propelled by rapid infrastructure modernization and stringent environmental mandates governed by the EPA. However, supply chain bottlenecks involving raw materials like stainless steel and alloy castings create operational friction, challenging manufacturers to optimize production cadences.
Emerging Trends Shaping the Isolation Valves Market
The industry is experiencing a profound shift toward intelligent automation and IIoT-enabled diagnostic tracking. Smart actuation reduces unplanned facility downtime, allowing operators to monitor cycle counts and seating wear remotely in complex petrochemical facilities.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain disruptions and deferred capital expenditures temporarily depressed project pipelines. Recovery has been accelerated by stimulus-backed municipal water upgrades and an aggressive rebound in global liquefied natural gas (LNG) terminal construction.
Competitive Landscape and Strategic Dynamics
Market concentration remains moderately fragmented, featuring tier-one engineering firms alongside agile regional manufacturers. Industry heavyweights like Emerson Electric Co. and Flowserve Corporation leverage extensive global distribution networks to secure large-scale EPC contracts.
Executive Summary of the Isolation Valves Market
Driven by robust industrial expansion, the Isolation Valves Market is projected to surge from $4.28 Billion in 2026 to $6.94 Billion by 2033, expanding at a notable 7.15% CAGR. Strategic M&A and portfolio diversification into cryogenic-rated designs remain paramount for sustainable growth.
Long-Term Market Forecast from 2027 to 2033
Our research forecasts accelerated expansion throughout the 2027 to 2033 timeframe, achieving the targeted $6.94 Billion valuation. This trajectory reflects sustained capital allocation toward hydrogen energy transport and greenfield seawater desalination plants.
Comprehensive Segmentation Analysis
Segmentation spans multiple categories: By Type (Ball Valves, Butterfly Valves, Knife Gate Valves, Plug Valves, Other Types), By Sales Type (Original Equipment and Aftermarket), By Operation Type (Automated and Manual), and diverse End-Use Industries. Each category addresses specific pressure-temperature ratings required by ASME and API standards.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights North America and Asia-Pacific as primary demand hubs. North America prioritizes shale gas infrastructure updates, while Asia-Pacific witnesses massive urbanization and power generation investments, particularly across industrial corridors in China and India.
In-Depth Regional Review of Growth Hotspots
Asia-Pacific leads volume consumption due to prolific wastewater treatment plant constructions. Meanwhile, Europe enforces stringent fugitive emission standards under ISO 15848, driving localized adoption of advanced bellows-sealed and triple-offset butterfly valve architectures.
Company Profiles and Strategic Market Positioning
Leading participants such as Crane Co., Velan Inc., and KITZ Corporation focus on proprietary metallurgy and corrosion-resistant coatings. Their strategic positioning emphasizes high-margin severe service applications within nuclear power and offshore extraction platforms.
Porter's Five Forces Analysis
Industry rivalry is intense, intensified by moderate buyer power among major EPC contractors. Threat of substitutes remains low due to strict certification prerequisites, whereas supplier power fluctuates based on raw material availability for exotic alloy forged bodies.
SWOT Analysis of the Isolation Valves Market
Strengths include high product durability and essential utility across energy sectors. Weaknesses involve high initial capital expenditure. Opportunities lie in renewable energy transition projects, while threats center on macroeconomic inflation and geopolitical trade tariff volatility.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw metal foundries supplying pig iron and nickel alloys, progressing through precision machining, automated actuation integration, and finally distribution to end-users across major petrochemical complexes and municipal authorities.
Investment Insights and High-Potential Areas
Investors should target niche manufacturers specializing in zero-leakage cryogenic valves for LNG carriers and automated slurry isolation valves for mining operations. These high-barrier segments command superior operating margins and insulate portfolios from cyclical downturns.
Conclusion and Key Takeaways
The Isolation Valves Market industry trends confirm that technological integration and environmental compliance are no longer optional. Companies adapting modular, IIoT-ready valve assemblies will capture disproportionate market share through 2033.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by combining customs trade registries, primary stakeholder interviews with chief engineering officers, and secondary macroeconomic indicators from international energy agencies to ensure econometric precision.
Scope of the Report and Analytical Parameters
This report evaluates global market dynamics across specified product categories and regional tiers from 2026 through 2033. Excluded from this scope are unverified artisanal valve workshops and non-industrial residential plumbing isolation hardware.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity highlights key strategic moves, including joint ventures between actuator specialists and valve foundries to streamline digital smart-valve production lines, alongside facility expansions by industry leaders targeting localized supply chain resilience.